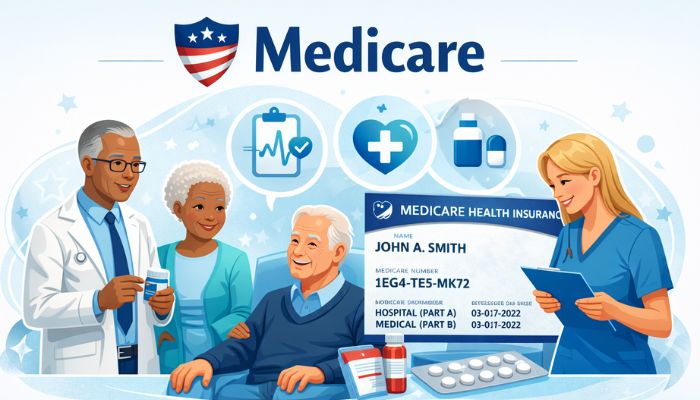
Securing affordable, comprehensive medical coverage is one of the most critical aspects of retirement planning. As healthcare costs continue to climb, navigating the complex world of federal insurance becomes paramount for older adults and individuals with specific health conditions. Medicare stands as America’s premier national health insurance program, currently providing vital medical coverage to over 65 million beneficiaries across the United States.
Learn about: Medicaid
If you are approaching retirement age, assisting an elderly loved one, or exploring ways to lower your out-of-pocket medical expenses, this definitive guide will break down the system, maximize your Medicare open enrollment options, and help you select the most lucrative plans available today.
What is Medicare and How Does Federal Health Insurance Work?
Established in 1965 under Title XVIII of the Social Security Act, Medicare is a federal health insurance program managed by the Centers for Medicare & Medicaid Services (CMS). Unlike Medicaid, which is a need-based program for low-income individuals, Medicare is an entitlement program primarily based on age or specific medical status, regardless of income.
Core Eligibility Requirements
To qualify for Medicare benefits, an individual must meet at least one of the following criteria:
-
Be 65 years of age or older.
-
Be a U.S. citizen or a legal permanent resident who has lived in the country continuously for at least five years.
-
Be under 65 with specific permanent disabilities and have received Social Security Disability Insurance (SSDI) benefits for 24 months.
-
Have End-Stage Renal Disease (ESRD) requiring permanent kidney dialysis or a transplant, or have Amyotrophic Lateral Sclerosis (ALS), commonly known as Lou Gehrig’s disease.
Understanding the Four Parts of Medicare: A Detailed Breakdown
Medicare is divided into four distinct components, each designed to cover specific medical resources and services. Understanding these segments is vital for avoiding costly gaps in coverage.
Part A: Inpatient Hospital Insurance
Medicare Part A handles the heavy lifting when it comes to institutional care. For most beneficiaries who have paid Medicare taxes for at least 10 years (40 quarters) through their working life, Part A is completely premium-free.
-
What it covers: Inpatient hospital stays, skilled nursing facility care, hospice care, and limited home health services.
-
Palabras clave de alto valor: Inpatient hospital insurance, skilled nursing facility care, Medicare Part A benefits.
Part B: Outpatient Medical Insurance
Medicare Part B covers standard medical services that occur outside of a prolonged hospital stay. Unlike Part A, Part B requires a monthly premium, which is adjusted annually based on the beneficiary’s income level.
-
What it covers: Doctor visits, preventative care (screenings and annual wellness visits), ambulance services, mental health care, and durable medical equipment (DME) like wheelchairs or oxygen tanks.
-
Palabras clave de alto valor: Outpatient medical insurance, medical equipment insurance, doctor visit coverage.
Part C: Medicare Advantage Plans
Medicare Advantage is an alternative pathway to receiving your benefits. These plans are sold by private, Medicare-approved insurance companies. When you choose Part C, the private insurer bundles your Part A, Part B, and usually Part D coverage into a single managed care plan (such as an HMO or PPO).
-
Why it is popular: Many Advantage plans offer zero-dollar premiums and include extra benefits not found in Original Medicare, such as dental, vision, and hearing care.
-
Palabras clave de alto valor: Best Medicare Advantage plans, private health insurance for seniors, zero premium Medicare Advantage.
Part D: Prescription Drug Coverage
Medicare Part D provides standalone prescription drug coverage through private insurance companies. Because Original Medicare (Parts A and B) does not cover most outpatient medications, enrolling in Part D is crucial to avoid steep pharmacy bills and lifelong late-enrollment penalties.
-
Palabras clave de alto valor: Medicare prescription drug plans, senior medication coverage, Medicare Part D enrollment.
Supplementing Your Coverage: What is Medigap?
Even with Parts A and B, Original Medicare does not cover 100% of your medical costs. Beneficiaries are still responsible for deductibles, copayments, and a standard 20% coinsurance fee for outpatient care. To shield themselves from catastrophic financial losses, many seniors invest in a Medicare Supplement Insurance (Medigap) policy.
How Medigap Fills the Financial Gaps
Medigap policies are standardized by the federal government but sold by private insurers. They are designed specifically to pay for your share of Original Medicare costs. It is important to note that you cannot hold both a Medicare Advantage plan and a Medigap policy simultaneously; you must choose one path or the other.
Navigating Enrollment Periods and Avoiding Lifetime Penalties
Timing is everything when it comes to registering for federal healthcare. Missing your windows can result in permanent premium increases.
1. Initial Enrollment Period (IEP)
This is your first opportunity to sign up for Medicare. It is a 7-month window centered around your 65th birthday—including the 3 months before you turn 65, your birthday month, and the 3 months immediately following.
2. General Enrollment Period (GEP)
If you missed your IEP, you can sign up during the General Enrollment Period, which runs from January 1 to March 31 each year, with coverage beginning the following month. However, you may face late-enrollment penalties that stay on your premium permanently.
3. Annual Medicare Open Enrollment Period
Running from October 15 to December 7 every year, this is the critical window where current beneficiaries can re-evaluate their coverage, switch between Original Medicare and Medicare Advantage, or alter their Part D prescription drug plans to lower their healthcare costs for the upcoming calendar year.